

AARP Hearing Center
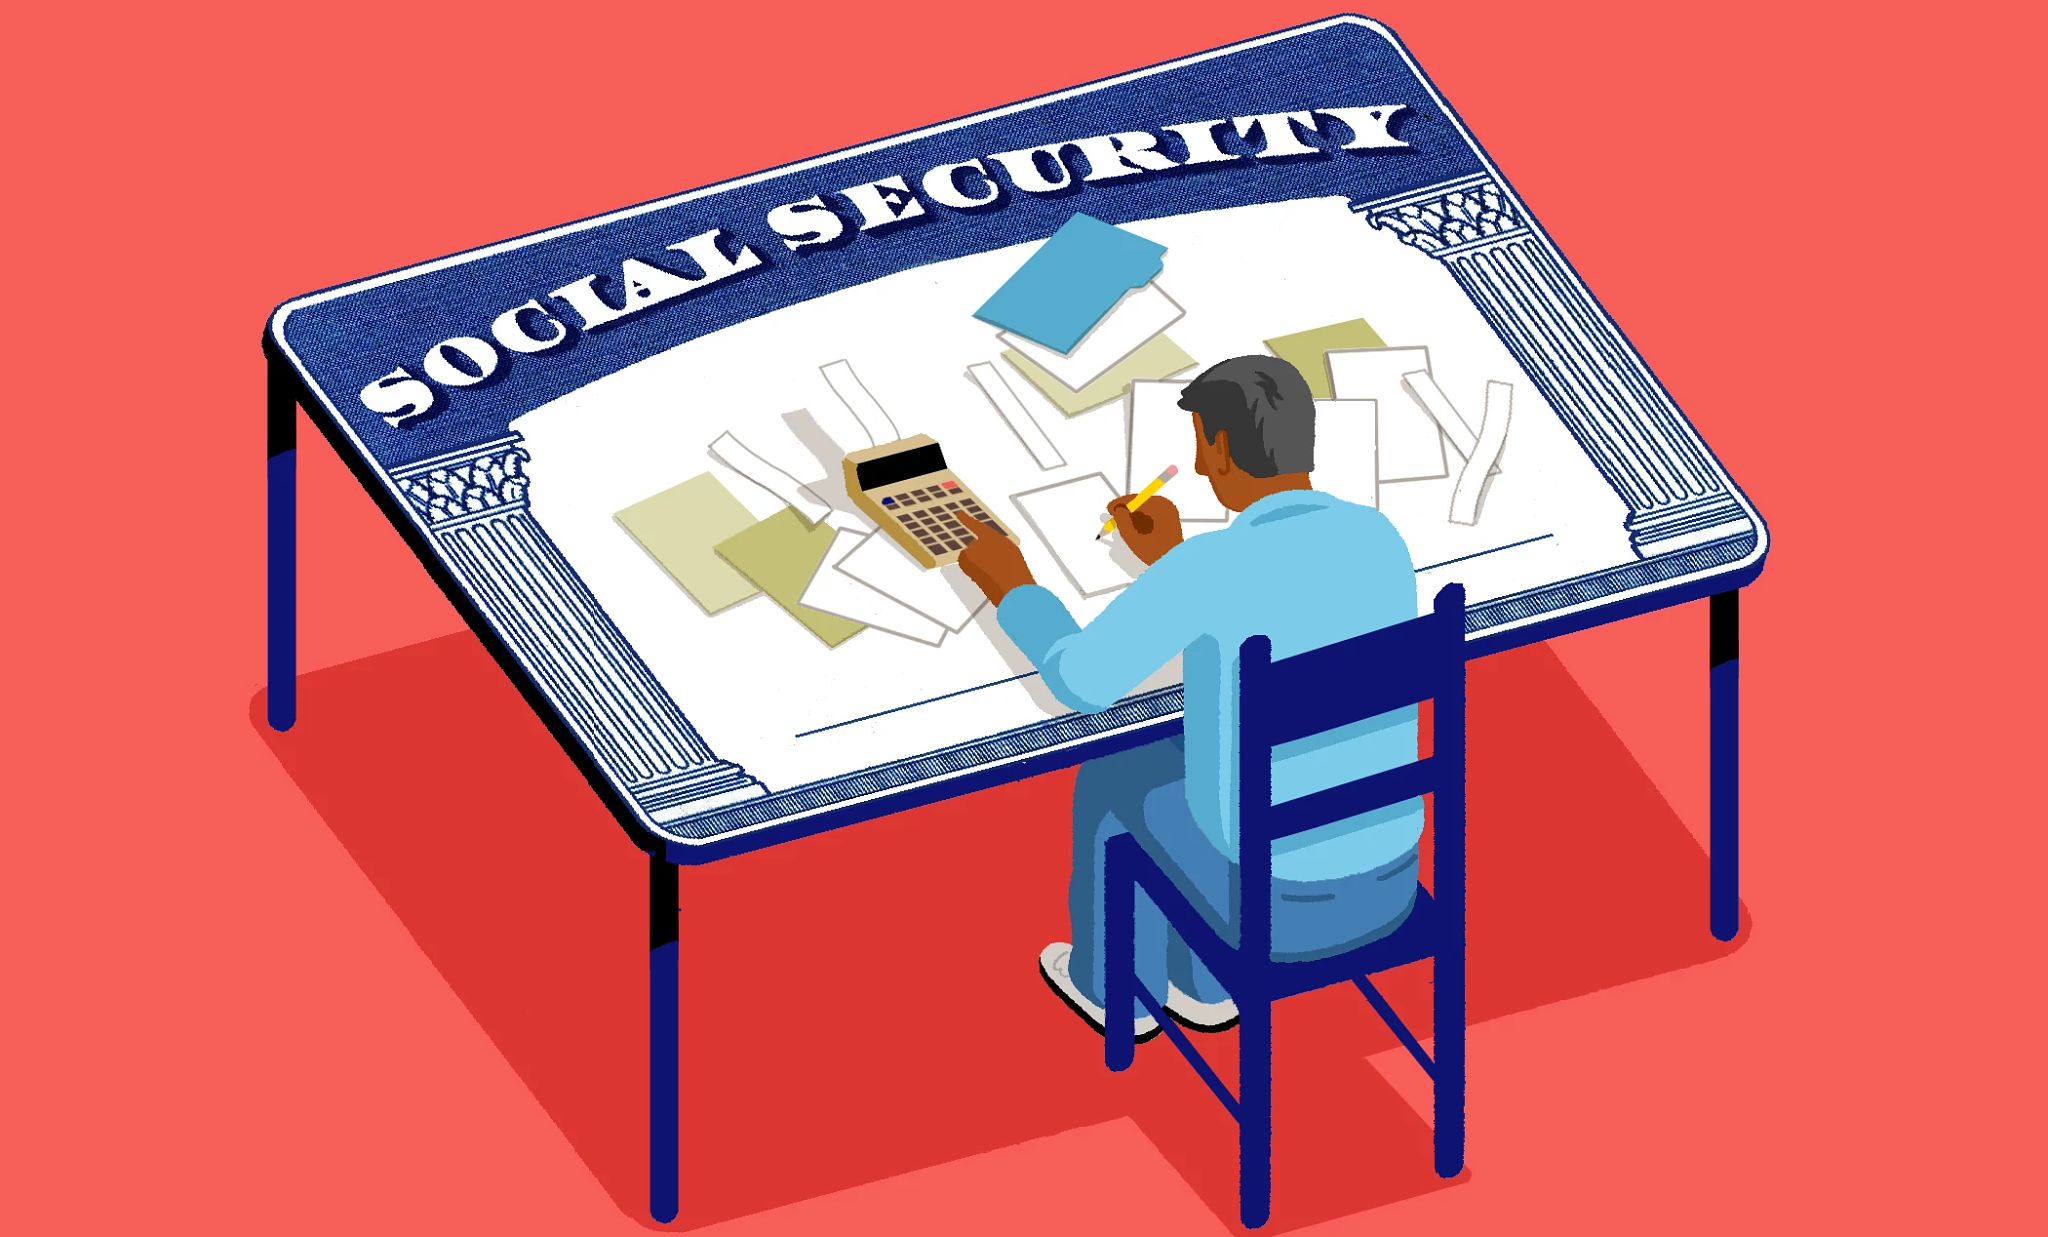













While unexpected expenses and the need for emergency savings has received increased attention in recent years, retirees face a unique set of challenges when an unexpected cost confronts them. Using the 2000–2020 Health and Retirement Study (HRS) and the 2001–2019 Consumption and Activities Mail Survey (CAMS), this report estimates unexpected expenses in three broad categories: (1) “rainy day” expenses, such as replacing an air conditioner or buying new tires; (2) family-related expenses, including financial transfers and changes in family structure; (3) and out-of-pocket health care costs, including long-term care. The report provides insights on how unexpected expenses affect retirement income adequacy and explores policy approaches that can help retirees absorb financial shocks without derailing their long-term security. Read the full report.
Key Takeaways:
- Most retirees face unexpected expenses each year, with such expenses equaling about 11% of annual income for the typical retired household.
- Unexpected expenses can quickly deplete savings and force retirees to make difficult trade-offs, particularly for those with limited income sources beyond Social Security.
- The burden from unexpected expenses is significantly greater for Black and Hispanic households as well as single-person households.
- Policies that incentivize systematic withdrawals or partial annuitization can help delay the decision to begin receiving Social Security benefits and reduce liquidity-longevity trade-offs, while broader access to health savings accounts and affordable long-term care insurance can help with health care costs in later years.
MORE FROM AARP


Does Saving for Emergencies Improve Productivity at Work?
This report uses data of the Understanding America Study (UAS), which explores the relationship between emergency savings–related behavior and workplace outcomes, to examine how financial insecurity may be reduced and workplace outcomes may be improved by helping workers to save for unexpected expenses.
