Money Saver
Where Is Her $70,000?
A woman’s investment has been locked up for a decade. Can she get her money back?
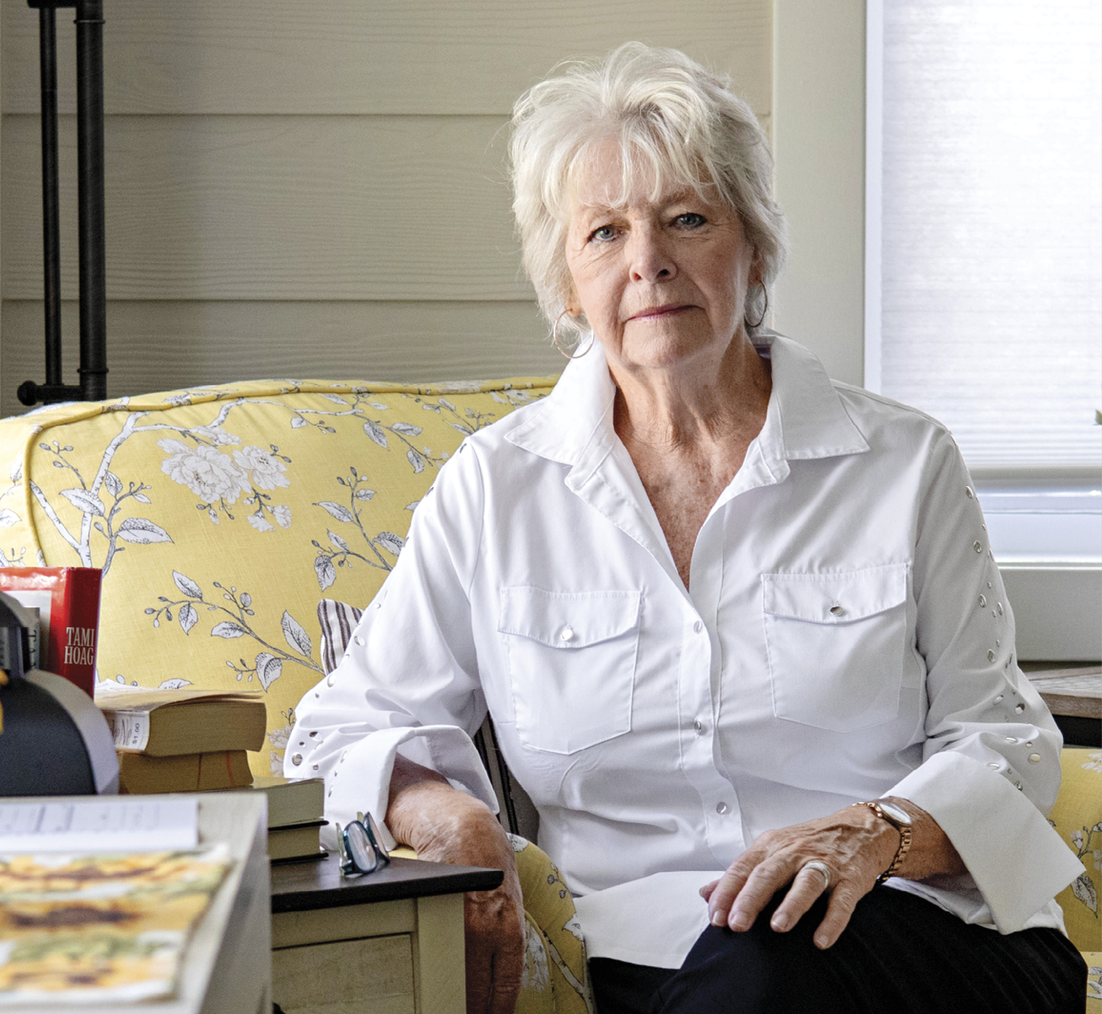
Spath says she didn’t understand her risks.
THE PROBLEM
About 10 years ago, a Wall Street broker that Susan Spath had been working with offered her a chance to invest in a company he was launching to provide financial services to people without bank accounts. It was her impression, Spath says, that the $70,000 she put in would bring her returns of about 10 percent annually, starting in two or three years. Now, a decade later, Spath, 77, has received no payments, and she can’t cash out. “I did not understand what I was getting into,” Spath wrote me.
THE ADVICE
Spath, a retired interior designer, made what is known as an illiquid investment. This big category encompasses assets that, unlike mutual funds, exchange-traded funds and publicly traded stocks, don’t change hands often and don’t have a big pool of ready buyers—think privately held companies or a piece of real estate.
Under U.S. Securities and Exchange Commission (SEC) rules for the type of offering the broker presented to Spath, the company could have an unlimited number of accredited investors (people with over $1 million in assets) and up to 35 non-accredited investors “capable of evaluating the merits and risks” of the investment. Spath didn’t have a million. Nor did Spath—who didn’t like the possibility of loss in the stock market, and who had previously worked with the same broker to buy bonds backed by churches—understand the risks; she says she wouldn’t have put money in if she thought she might lose it. The broker says Spath signed documents clearly acknowledging a high risk of loss. He also says that the 10 percent returns Spath alluded to were possible increases in an ownership stake, not cash payments.
On BrokerCheck, a website run by FINRA, Wall Street’s self-regulatory organization (brokercheck.finra.org), I found that the broker’s license was valid when he sold Spath the investment but had lapsed in 2017. A 2016 filing in the SEC’s database of company reports (sec.gov/edgar/search) indicated that the new operation had raised $130,000, all from five non-accredited investors.
I phoned the firm that houses the IRA holding Spath’s investment. A supervisor told me that on their books, the value of Spath’s investment had grown by 10 percent a year to nearly $140,000. Spath—who was surprised to learn last year that the investment was in an IRA—must use that figure to calculate her required minimum distributions; she has had to pull money from a different IRA to avoid penalties.
When I called Spath’s former broker, he insisted Spath knew about her risks. “Starting a business sometimes doesn’t happen the way you think,” he said. At that time, and in later correspondence, he stated that the company would consider buying back all or part of Spath’s ownership stake, but made no guarantees. “The company continues to work toward solvency,” he added.
Michael Bixby, a Pensacola, Florida, securities attorney and president of the Public Investors Advocate Bar Association, says the time to take action on an investment you’re worried about is as soon as you suspect there’s a problem. Reach out to the broker’s branch manager, call FINRA’s Securities Helpline for Seniors (844-574-3577), or go online to finra.org/investors/need-help to file a complaint.
If that doesn’t work, find a lawyer who’ll take on your case (for a contingency fee of up to 40 percent, typically) and go to arbitration. But even if you win, there’s no guarantee you’ll recover your money. In 2024, FINRA reported that one-quarter of people who won arbitration cases did not get paid.
THE OUTCOME
As of this writing, Spath was mulling over her options. If you’re considering an illiquid investment, be careful. Financial planner Cary Carbonaro, for example, says that when her clients want to make an illiquid investment, she limits the amount to 5 percent of their wealth.
Want Jean Chatzky to write about helping you sort out your financial problem? Email rescue@aarp.org.